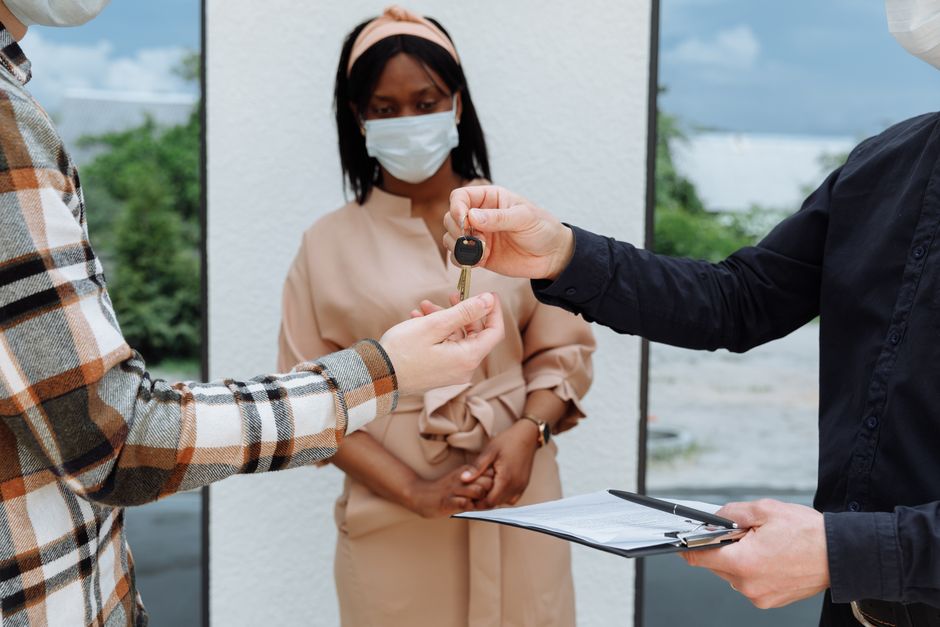
At the end of a car lease you give the car back and walk away. The funder arranges free collection, an inspector checks the vehicle against BVRLA fair wear and tear standards, and you pay only for excess mileage or damage beyond those standards. There's no balloon payment, no part-exchange haggling and nothing to sell.
What's in this guide
- What actually happens when your lease ends?
- When does the leasing company get in touch?
- What are your options at the end of a car lease?
- How does collection and inspection work?
- What could you be charged at the end?
- What counts as fair wear and tear?
- How are excess mileage charges worked out?
- Your end-of-lease checklist
- What if you disagree with a charge?
- Frequently asked questions
Key Takeaways
- The car goes back to the funder (the finance company that owns it) on or around your contract end date. Collection is normally free and arranged for a date and address that suits you.
- An independent inspector appraises the vehicle against the BVRLA Fair Wear and Tear standard. Normal ageing costs you nothing; damage beyond the standard is chargeable.
- Excess mileage is pure arithmetic - miles over your total allowance multiplied by the pence-per-mile rate printed in your agreement. Rates commonly sit between 3p and 30p per mile depending on funder and vehicle.
- Contract hire has no purchase option, though some funders will sell the car through a third party. Your realistic choices are: hand back and re-lease, hand back and stop, or extend the contract for a few months.
- Start the process 10-12 weeks out. That's enough time to fix a kerbed alloy cheaply and to get a new car ordered before the old one leaves your driveway.
What actually happens when your lease ends?
Three things, in order. Your funder contacts you a few months before the end date to book collection. On the agreed day a driver collects the car from your home or work and it's appraised against BVRLA standards. Then, a few weeks later, you either hear nothing or receive an invoice for excess mileage and any chargeable damage.
That's the whole process. It catches people out because it's so much less dramatic than the end of a Personal Contract Purchase (PCP) - the finance type where you can pay a large final balloon payment to own the car. Contract hire has no balloon. The funder owns the vehicle throughout, carries the risk on what it's worth at handback, and takes it back to sell at auction or through the trade.
Your monthly rentals stop after the final one. Direct debits normally cease automatically, though it's worth checking your bank rather than assuming. And your obligations - insurance, servicing, keeping the car roadworthy - run right up to the moment the collection driver signs for it, not to the date of the last payment.
One point that trips up a lot of drivers: the contract end date and the collection date are rarely the same. If collection slips past your end date, most funders will charge pro-rata for the extra days at your normal rental rate. Ask what happens if the collection agent can't come on time.
When does the leasing company get in touch?
Most funders make first contact somewhere between three and six months before your contract end date, usually by letter or email, confirming the end date and asking how you'd like to proceed. Our team typically gets in touch around the same point to talk about what's next, so you're not making decisions in a rush.
Use that window properly. Lead times on new cars vary enormously - some models are in stock and delivered within days, others are factory orders measured in months. If you want a seamless changeover, start looking at your next vehicle at least three months out. FVL's in-stock lease cars exist precisely for people who left it later than they meant to.
What should you be doing at each stage?
6-4 months out
Check your mileage against your total allowance. Decide roughly what you want next - same car, smaller car, electric. Start browsing.
12-8 weeks out
Appraise the car in daylight after a wash. Book any smart repairs, outstanding servicing or an MOT. Order your next vehicle.
Final 4 weeks
Confirm the collection date, find both keys, the handbook and service records, gather charging cables and remove personal data.
The BVRLA's own consumer guidance recommends appraising the vehicle 10-12 weeks before it's due back, which gives you time to sort anything unacceptable. That's the single most useful thing in this guide. Ten minutes with a bucket of water and a torch, three months early, is worth more than any amount of arguing after collection.
What are your options at the end of a car lease?
Four, realistically: hand the car back and lease something new, hand it back and stop driving that vehicle entirely, extend the current contract for a few months, or - occasionally, and never as a contractual right - buy the car through a third party the funder nominates. Contract hire itself contains no purchase option.
| Option | How it works | Best for |
|---|---|---|
| Hand back and re-lease | Old car collected, new car delivered - often on the same day if timings are planned. | Most drivers. Keeps you in a car under warranty with a known monthly cost. |
| Hand back and stop | Car collected, charges settled, contract closed. Nothing else to do. | Changing circumstances - moving abroad, city living, a company car starting. |
| Extend the contract | Funder agrees a short extension, usually month-to-month or a fixed few months, with a pro-rata mileage allowance. | Bridging a gap while a factory-order replacement is built. |
| Buy the vehicle | Some funders will sell via a nominated dealer or disposal partner at a price they set. Many won't sell at all. | Rare cases - unusual spec, a car you've grown attached to, or a favourable market. |
Extensions are worth understanding properly, because they're the option people forget. If your replacement is three months away, an extension is almost always cheaper and simpler than the alternatives. Rentals sometimes rise slightly on an extension, sometimes stay flat, and occasionally fall - it depends on the funder's view of the car's current value. Ask early; some funders need notice to set one up. We cover this in more depth in our guide to what your options are at the end, and the purchase question in can I buy my car at the end of the lease?
Thinking about going electric next?
An end-of-lease changeover is the natural moment to switch. Company car Benefit-in-Kind (BiK) - the tax you pay on a car provided by your employer - sits at 3% of list price for fully electric cars in the 2025/26 tax year, rising to 4% in 2026/27 and 5% in 2027/28 under HMRC's published company car tax rates. Petrol and diesel cars are taxed on a scale that runs to roughly 15-37% of list price depending on CO2 emissions.
For employees, that gap is what makes salary sacrifice so effective, and for sole traders and limited companies it's why business contract hire on an EV looks so different to a petrol equivalent.
How does collection and inspection work?
The funder books a collection agent to come to your home or workplace on an agreed date. The driver walks around the car with you, records its condition and mileage, takes photographs, and asks you to sign a collection note. Some funders inspect fully on the driveway; others collect first and appraise later at their own site.
Be there. The BVRLA specifically recommends being present at collection so you and the agent can check and agree the vehicle's condition together. If you're not, you lose the chance to challenge anything on the spot, and a mark you'd have pointed out as pre-existing becomes much harder to argue about later.
Practical points from the collections we've seen go wrong: take your own timestamped photographs of every panel, all four wheels, the interior and the odometer before the driver arrives. Don't sign a blank or pre-completed condition note. And if the agent notes something you disagree with, write your disagreement on the form before signing rather than signing and phoning afterwards.
The car must be taxed, insured and - if it's over three years old at collection - carry a valid MOT. Under DVLA rules the funder is the registered keeper, so vehicle tax is usually their responsibility on a contract hire agreement, but insurance is firmly yours until the moment the vehicle is handed over. Cancel the policy the day after collection, not the day before. Our step-by-step walkthrough of the lease return process covers collection day in detail, and preparing for your end-of-lease inspection covers what the appraiser is actually looking at.
What could you be charged at the end?
Four things, and only four: excess mileage, damage beyond fair wear and tear, missing items such as keys, charging cables or the service book, and outstanding rentals or arrears. There's no admin charge for the handback itself with most funders, and there is never a charge for normal wear.
| Charge | How it's calculated | Can you avoid it? |
|---|---|---|
| Excess mileage | Miles over the contracted total × the pence-per-mile rate in your agreement | Only in advance - ask about a mileage amendment mid-contract |
| Damage charges | Cost of rectifying damage outside the BVRLA standard | Yes - repair it properly before collection, usually for less |
| Missing items | Replacement cost of second keys, cables, locking wheel nut, handbook, parcel shelf | Yes - find them. Second keys are the most common casualty |
| Late return / arrears | Pro-rata rental beyond the end date, plus any unpaid rentals | Yes - book collection early and check your final direct debit cleared |
According to BVRLA guidance, end-of-lease charges compensate the leasing company for rectifying damage or missing items, and can still be applied where the funder decides for commercial reasons not to repair the car before selling it. That surprises people - the argument "but they didn't even fix it" doesn't hold, because the loss is in the car's sale value, not in a repair bill.
Honestly? Most handbacks we see result in either no charge at all or a modest one. The bills that hurt come from two sources: mileage that was underestimated at the outset, and a driver who never looked at the car properly until the transporter arrived.
What counts as fair wear and tear?
Fair wear and tear is deterioration caused by normal use - light stone chips, small scuffs within defined limits, evenly worn tyres above the legal minimum. It is not damage, which the BVRLA defines as the result of a specific event or series of events: impact, harsh treatment, badly stowed loads, negligence or omission. You're never charged for the first category.
The BVRLA Fair Wear and Tear Guide is the industry standard used by essentially every UK funder, and it's genuinely specific: it covers bodywork, paint, glass, lights, tyres and wheels, the interior, controls and documentation. Broadly, small areas of chipping including door edge chips are acceptable, while dents on the roof or along a swage line are not, and any chip or scratch requiring a full panel or bumper to be repainted falls outside the standard.
The items that catch most people out
- Kerbed alloys. Easily the most common charge. A smart repair costs a fraction of the funder's rectification charge.
- Windscreen chips. Often covered by your insurance for a small excess. Left alone, they crack.
- Tyres. Must be legal, undamaged and evenly worn - and matched to the manufacturer's specification. Budget tyres on a premium car can be queried.
- Missing second key. Replacing a modern key with immobiliser coding is not cheap. Start looking for it now, not on collection morning.
- Servicing. A gap in the service history is a chargeable failure to maintain the car as agreed.
Full detail sits in our guides to fair wear and tear and avoiding end-of-lease damage charges. Ask your funder for their copy of the BVRLA guide - they're obliged to make it available.
How are excess mileage charges worked out?
Total miles allowed equals your annual allowance multiplied by the contract length. Subtract that from the odometer reading at collection, then multiply the excess by the pence-per-mile rate printed in your agreement. It's fixed contract arithmetic, set the day you signed, and it isn't negotiable at handback.
Illustrative example: a three-year contract at 10,000 miles a year allows 30,000 miles in total. Hand the car back showing 34,000 miles and you're 4,000 miles over. At an excess rate of 10p per mile, that's 4,000 × £0.10 = £400. At 20p per mile it would be £800. Figures are illustrative only - your own rate is in your agreement.
Two things worth knowing. First, the allowance is assessed over the whole term, not year by year - drive 15,000 in year one and 5,000 in year three and you're fine. Second, rates vary widely by funder and vehicle: published UK guidance puts the typical range at roughly 3p to 30p per mile, with premium models generally at the higher end.
What if you know you'll go over?
Ring your funder as soon as you spot the trend. Many will agree a mileage amendment mid-contract, reissuing the agreement with a revised allowance and a revised rental. Whether that beats simply paying the excess depends on your rate - do the sum both ways. Leave it until the final quarter, though, and an amendment usually costs more than the charge it was meant to avoid.
Your end-of-lease checklist
Work through this in the final 10-12 weeks and you'll remove almost every avoidable charge. Nothing here is complicated - it's just easy to leave until the week of collection, which is exactly when repairs cost the most and second keys stay lost.
The car
- Wash it and appraise in good daylight
- Book smart repairs for kerbed wheels and scuffs
- Check tyre tread and damage, including the spare
- Service and MOT up to date and stamped
- No warning lights showing on a test drive
The paperwork and kit
- Both keys, plus the locking wheel nut
- Handbook, service records, MOT certificate
- All charging cables for an EV or plug-in hybrid
- Parcel shelf, boot floor, load cover, original alloys if you changed them
- Personal data deleted from the infotainment and paired phones removed
Two small ones that get forgotten every time: remove your toll or parking tags, and take the dashcam - including the hardwired cable, because a dangling wire behind the trim is a genuine mark against the interior standard.
What if you disagree with a charge?
Challenge it in writing to the funder first, with your own photographs and the collection note. Ask for the inspection report, the photographs the appraiser took, and a breakdown of how the charge was calculated against the BVRLA standard. Most disputes are settled at this stage. If it isn't, escalate.
Where the funder is a BVRLA member, the association operates a conciliation service for members and their customers to help resolve disputes once the company's own complaints process has run its course. Separately, regulated consumer agreements give you access to the Financial Ombudsman Service. As an FCA-authorised and regulated broker, we're also bound by our own complaints procedure, and our team will happily help you frame a challenge to a funder even though the charge itself isn't ours to waive.
Be realistic about what's winnable. Excess mileage isn't - it's odometer arithmetic against a rate you agreed. Damage assessments are, because condition is a judgement call, and a clear photograph taken before collection is the strongest evidence there is.
Lease ending? Let's line up what's next
Our team has been arranging leases for over 25 years, and the smoothest changeovers are always the ones planned three months out - old car collected in the morning, new one delivered in the afternoon. Tell us what you need from a car and what you want to spend, and we'll show you where the strongest value sits.
Call 0333 003 3325 or browse the current offers.
Frequently Asked Questions
Sources
- Returning your leased vehicle - consumer advice - British Vehicle Rental and Leasing Association
- Getting an MOT - GOV.UK
- Calculate tax on company cars - HMRC / GOV.UK
- Excess mileage charges explained - Carwow
Written by the leasing team at First Vehicle Leasing, an FCA-authorised and regulated vehicle leasing broker and BVRLA member with over 25 years' experience arranging car and van contract hire for UK drivers and businesses. Questions about your handback? Call our team on 0333 003 3325.
Will I be approved?
Five questions, no sign-up, and an honest answer before you apply for anything.
Check my eligibility
