A car leasing comparison should take about ten minutes and save you a few hundred pounds. The trick is knowing which numbers actually matter and which ones are just noise. Below, our experts at First Vehicle Leasing set out how to compare personal and business lease deals properly, and what to check before you sign anything.
Key Takeaways
- A lease comparison only works when the term, annual mileage and initial rental are identical across every quote. Change one and the monthly figure stops being comparable.
- Personal Contract Hire (PCH) prices are shown including VAT. Business Contract Hire (BCH) prices are shown excluding VAT, so never compare the two side by side.
- Under HMRC's published company car tax rates, a fully electric company car is taxed at 4% of P11D value in the 2026/27 tax year, against roughly 15-37% for petrol and diesel.
- A quick value test: divide the car's list price by the monthly rental on a 9+35 profile. Above 90 is strong, 80 to 90 is reasonable, below 80 means keep looking.
- Check the broker is on the FCA register and signed up to the BVRLA Leasing Broker Code of Conduct before you hand over any details.
What Should You Compare on a Car Lease Deal?
Compare five things and nothing else matters much: the contract term, the annual mileage allowance, the initial rental, the monthly rental, and whether maintenance is included. Every one of those changes the monthly price, so two quotes are only meaningful against each other when all five line up.
Most people fixate on the monthly figure alone. That's how a deal that looks £40 cheaper turns out to be a 10,000-mile contract when you drive 15,000. Excess mileage charges are set out in your agreement in pence per mile, and they add up quickly at the end of a three-year term.
| What to compare | What to check | Why it matters |
|---|---|---|
| Initial rental | Is it 1, 3, 6, 9 or 12 months' rental upfront? | A bigger upfront payment lowers the monthly figure. It doesn't lower the total cost. |
| Contract term | 24, 36 or 48 months | Longer terms usually mean lower monthlies, but you're committed for longer. |
| Annual mileage | Be honest, then add a small buffer | Excess mileage is charged per mile at the end. Guessing low is a false economy. |
| Maintenance | Included or not, and what it covers | Servicing and tyres bundled into the rental change the comparison entirely. |
| Admin and delivery fees | Ask for the total payable, in writing | Fees sit outside the advertised monthly price at some brokers. |
How Can You Tell a Good Lease Deal From an Average One?
Divide the car's list price by the monthly rental. The answer tells you how many monthly payments fit into the price of the car, and higher is better. Above 90 is strong value, 80 to 90 is reasonable, and below 80 means you should keep looking. Assume a 9+35 profile unless stated otherwise.
A 9+35 means nine months' rental paid upfront, then 35 monthly payments. Here's an illustrative example: a car with a £30,000 list price at £320 a month on 9+35 scores 93.75, which lands in strong territory. The same car at £360 a month scores 83.3 - reasonable, nothing special.
And this only works like for like. A 9+35 can only be compared with another 9+35, on the same term and the same mileage. Set a 9+35 against a 1+35 and the score is worthless, because the deal with more money upfront will always flatter itself. Keep the VAT basis consistent too: ex-VAT rental against ex-VAT list price, or inc-VAT against inc-VAT. Never mix them.
Internationally, consumers use a "1% rule" - a monthly payment at or below 1% of list price marks a strong deal. It's the same test inverted, since a score of 100 is exactly 1%. Treat it as an informal rule of thumb rather than an industry standard.
Should You Compare Personal or Business Lease Deals?
If you're a sole trader, partnership or limited company and the car will be used for business, compare Business Contract Hire (BCH). Everyone else should compare Personal Contract Hire (PCH). The difference isn't cosmetic - BCH prices exclude VAT and carry tax treatment that PCH doesn't.
| Feature | Personal (PCH) | Business (BCH) |
|---|---|---|
| Advertised price | Includes VAT | Excludes VAT |
| VAT reclaim | None | VAT-registered businesses can typically reclaim 50% of the VAT on rentals for a car with private use, and 100% on the maintenance element |
| Corporation tax | Not applicable | Rentals are an allowable expense; 15% is disallowed for cars emitting over 50g/km CO2 |
| Company car tax (BIK) | None | Benefit in Kind (BIK) applies where there's private use - 4% of P11D value for a pure EV in 2026/27 |
| Credit check | Personal | Business, sometimes with a director's guarantee |
Benefit in Kind is the tax an employee pays on a company car available for private use. It's the car's P11D value (list price including VAT and delivery, excluding first registration fee and VED) multiplied by an HMRC percentage set by CO2 emissions, then by your income tax rate. For petrol and diesel cars that percentage runs roughly 15-37%. For a fully electric car in 2026/27 it's 4%, rising by one point a year to 5% in 2027/28. You can check your own figure with GOV.UK's company car tax guidance.
That gap is why so many business drivers land on an EV. If your employer offers it, salary sacrifice takes the rental from gross pay and stacks the National Insurance saving on top of the low BIK rate.
Why a Broker Beats Going Direct
A lease rental isn't the price of the car spread out. You pay the gap between what the vehicle costs to acquire and what it's forecast to be worth at the end of the term, plus interest charges.
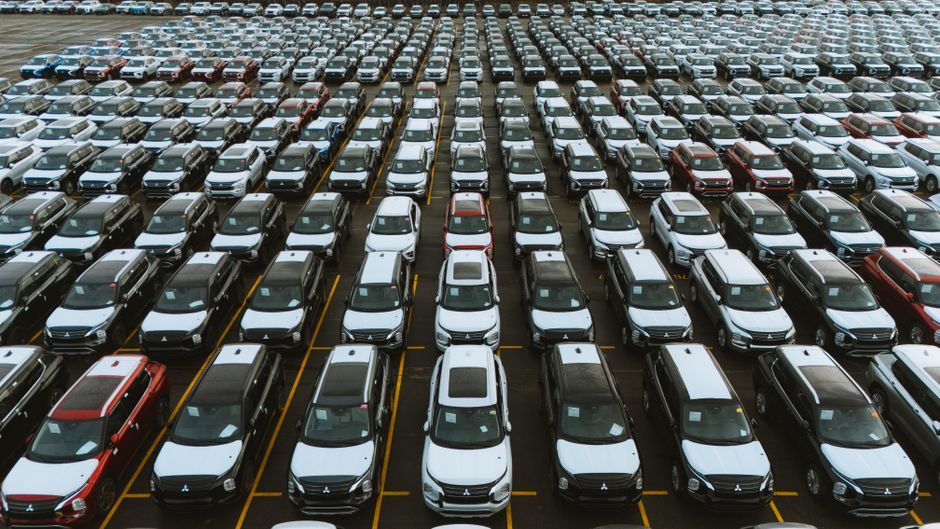
That's where volume buying counts. FVL commits to manufacturers in bulk - hundreds of vehicles at a time - on terms an individual, or a business taking one or two cars, can't replicate. Crucially, the end value is forecast against the vehicle itself, not against what the funder paid for it. So the discount comes off the front end while the residual stays put, narrowing the gap you fund.
You also hand the residual value risk to the funder. If the car is worth less than forecast at handback, that's their problem, not yours.
So Where Does the Best Value Actually Sit?
On the cars a broker has bought in depth. Most people no longer shop for one specific model - they want the best car for the money. Our leasing experts recommend deciding what you need from a vehicle and what you can spend, then looking at what represents the best value inside that, rather than fixing on one badge first.
On an ordinary model we haven't committed volume to, the terms will still beat what you'd arrange alone. They just won't match the special offers. Widen the shortlist and the numbers usually improve.
Your Car Lease Comparison Checklist
Before you compare leasing quotes from anyone, fix your variables first. Decide your term, mileage and initial rental, then ask every provider to quote on exactly that. It sounds obvious. In our experience it's the single thing most first-time leasers skip.
Fix the profile
Pick your term, mileage and initial rental before you look at a single price. Quote everything on that basis.
Match the VAT basis
Inc-VAT personal prices against inc-VAT. Ex-VAT business prices against ex-VAT. Mixing them is the classic error.
Ask for total payable
Initial rental plus all monthlies plus any admin or delivery fee. One number, in writing.
Check the credentials
Look the firm up on the FCA's Financial Services Register and confirm BVRLA membership.
Some practical scenarios. If you drive fewer than 10,000 miles a year, a shorter 24-month term on a lower mileage band often prices better than stretching to 48 months. If your job or income might change within three years, keep the initial rental low even though the monthly looks worse - flexibility has a price and it's usually worth paying. If you're weighing this against a purchase, read our leasing versus buying comparison first, because leasing isn't automatically cheaper for someone who keeps a car for eight years.
Ready to Compare Lease Deals?
Tell our team your budget, your mileage and roughly what you need the car to do. We'll come back with options across manufacturers on a like-for-like profile, so the numbers actually mean something.
Call 0333 003 3325 or browse the current offers online.
Frequently Asked Questions
Sources
- Tax on company benefits: company cars - GOV.UK
- Financial Services Register - Financial Conduct Authority
- Leasing Broker Code of Conduct - BVRLA
Written by the leasing team at First Vehicle Leasing, an FCA-authorised and regulated broker and BVRLA member with over 25 years arranging personal and business vehicle leases across the UK.